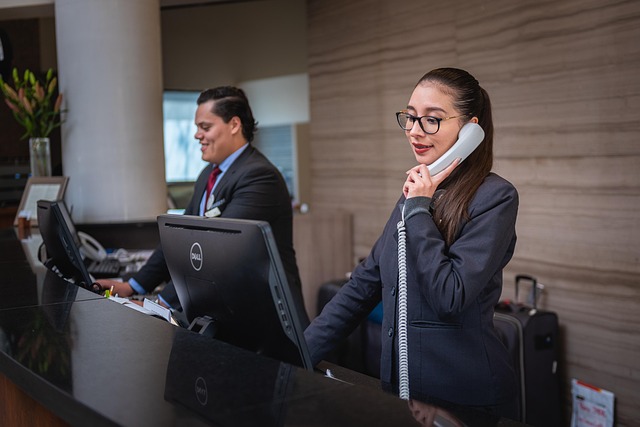
Occupancy, average daily rate and revenue per available room all climbed in the final week of October, capping a strong finish to the month for the U.S. hotel industry — even as international demand and higher prices continue to test the market.
Published: November 13, 2026 | U.S. Hotel Performance
The News
The U.S. hotel industry closed October on a notably high note. For the week ending October 31, occupancy reached 61.8 percent, average daily rate came in at $164.95, and revenue per available room — the industry’s headline performance metric — hit $101.88. RevPAR for the week grew nearly 10 percent year over year, according to the latest U.S. hotel performance data.
That is not a routine weekly print. For most of the past two years, the U.S. lodging recovery has been steady but uneven: occupancy gains of one to two points, rate growth that barely kept pace with inflation, and wide gaps between resort and urban markets. A near-double-digit weekly RevPAR increase signals that demand is finally outrunning the discounts operators used through the slower 2024–2025 stretch.
Three things are working in the industry’s favor right now. First, rate: pushing ADR toward $165 without a collapse in occupancy suggests operators have genuinely reclaimed pricing power, particularly in resort, group and premium-cabin-of-hospitality segments. Second, mix: the travelers filling rooms this fall are skewed toward higher-spending leisure guests and business groups rather than the lowest-yield transient segments. Third, supply: new-room growth remains historically low, so incremental demand converts almost directly into occupancy and rate rather than being spread thin across additional inventory.
The caveat is that weekly data can be noisy. One strong week does not confirm a trend — holiday-event calendars, convention cycles and even weather can inflate a seven-day comparison. Hotels that ran a major event in the last week of October 2026, or that face soft comparisons ahead, should resist assuming every week of the fourth quarter will look like this one. Month-to-date and rolling-quarter trends are the more reliable read.
Still, the week’s result lands alongside other positive signals: extended-stay hotels are posting their best occupancy gains in more than a decade, and major brands have raised full-year outlooks on the back of improving business travel.
What it means for hotel and travel businesses
For owners and operators: This is the week to protect rate. Smaller portfolio players that discounted into the fall may have left revenue on the table while the market supported gains. Revenue teams should re-examine late-October and November booking curves with fresh eyes — if demand is strong at $164.95 system-wide, sub-market pricing may be too timid. In the quarter’s final stretch, revenue-management discipline (especially on shoulder nights and Thursday arrivals) is worth more than incremental marketing spend.
For hotel investors: Rate-driven RevPAR growth is higher-quality growth than occupancy-driven growth. It means existing assets can produce more revenue without operating leverage hurting — no added housekeeping turns or banquet labor. Watch whether the rate gains hold through the typically softer mid-November window; if they do, 2027 underwriting assumptions deserve a revisit.
For brands and franchise leaders: Strong weekly performance is a selling point in pipeline conversations. Owners weighing a flag conversion are most receptive in strong-demand periods where brand-level distribution and group sales engines can compound upside. Communicate the performance story now.
For travel sellers and advisors: Strong demand plus higher rates means inventory tightens earlier. Advisors should be locking holiday-season and early-2027 inventory now rather than waiting for post-election or panic discounting that may simply never arrive.
The risk to monitor: International and international-adjacent demand remains a drag. Overseas visitor spending is projected to fall meaningfully in 2026, and higher travel prices are compounding that. The current strength is being carried by domestic leisure, group and corporate demand. If any of those soften, the industry has little inbound cushion.
Key numbers
- Occupancy, week ending Oct. 31: 61.8%
- Average daily rate: $164.95
- RevPAR: $101.88
- Weekly RevPAR growth: ~+10% year over year
More Stories
Marriott Lifts 2026 Revenue-Growth Forecast on Strong Travel Demand
Italy Tightens Access at Historic World Heritage Sites
Croatia Leads with Dubrovnik and Coastal Demand